I am not an accountant, so my view on the NNPC's recent 2025 financial report is not expert. It is good to know that PwC, the audit firm that approved the report, believes it truly reflects how the corporation performed based on Nigeria's standards. I found it comforting when a former colleague said, “Wonderful! While I was working in the bank, as the Corporate Banking Group’s relationship manager for the NNPC, the ‘most recent’ financials we had was about 15 years old.” That was 15 years ago. So in terms of accountability and public disclosure, Nigeria's top corporation over the past 49 years is making steady progress.
That said, some parts of the report showing a profitable company with better production are not clear. It is reasonable to say that the report’s profit growth figure may exaggerate the corporation’s real trading performance. Why is there confusion? The NNPC Group’s net profit grew by about 33 percent to ₦7.2 trillion last year, even though revenue dropped by 23 percent from ₦45.1 trillion in 2024 to ₦34.5 trillion last year. Gross profit also fell by the same percentage to ₦9.4 trillion in the same time. While two different factors, a ₦5 trillion rise in other income and a ₦1 trillion drop in general expenses, explain this strange situation, the issue is not that the profit increase came from more sales or gross profits. It is more about how consistent will the ‘other income’ performance be in future reports?
The corporation's balance sheet shows a complicated picture. With a current ratio of about 0.85, the NNPC’s short-term assets (₦28.1 trillion) do not fully cover its short-term liabilities (₦33.2 trillion). With the right timing, depending on its payables and receivables, the corporation should be able to meet its obligations. This balance sheet setup also explains the corporation’s cash issues. The group’s cash balance dropped from ₦10.3 trillion in 2024 to ₦6.4 trillion by the end of 2025. This happened even as cash generated from operations rose from ₦11.0 trillion the previous year to ₦12.9 trillion in 2025. Trade and other receivables dropped from ₦31.4 trillion in 2024, but even at ₦19.7 trillion last year, it was still large.
On the bright side, there is strong evidence that production is recovering. Still, the good news is challenged by the report's claim of an average crude and condensate production of 1.77 million barrels per day, a five-year high, and the financial highlights showing 565.8 million barrels of crude oil production. If you annualize that, the latter number means about 1.55 million barrels per day of production. I believe these two numbers refer to different scopes, national production versus the NNPC’s own production. Either way, the report could have made this clearer. It would also help if natural gas production was directly linked to segment revenue, investment returns, and cash generation.
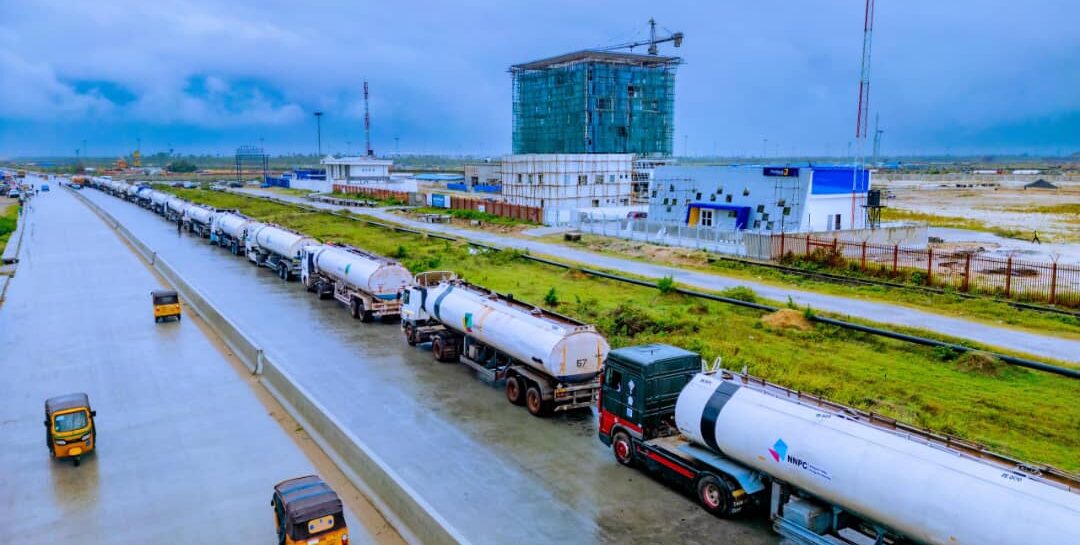
Overall, the NNPC report shows good operating progress. The cash generation from operations is especially impressive. Still, the drop in revenue and gross profit, the fact that profit growth is mostly due to large other income performance, and the current liabilities being much higher than current assets make the headline profit an incomplete measure of the organization’s financial strength.
For over ten years now, the main topic when discussing NNPC’s accounts has been the costs related to the subsidy for petrol prices. This is why I paid close attention to the corporation's report for last year, to see if the numbers back up the federal government’s claim of completely removing the subsidy. How do the numbers compare? The corporation’s financial statements still use terms like “energy security” and “under-recovery.” These terms are not exactly the same. Energy security costs may cover more than just the petrol price support.
Interestingly, the NNPC’s financial statement for 2024 shows ₦8.67 trillion as an “under-recovery” balance. Other parts of the 2025 statement call the same amount ₦8.67 trillion a “federation receivable.” These labels and reporting periods are not the same, but if either means that the corporation still covers the gap between petrol’s supply cost and a managed selling price and sees it as recoverable from the federation, the economic burden from the fuel subsidy has not gone away. It has just been taken on by the NNPC or the federation instead of being fully passed on to consumers.
Drop your comment
No comments yet — be the first to drop the gist 👇